MoneyPilot : Class Action

Screenshots
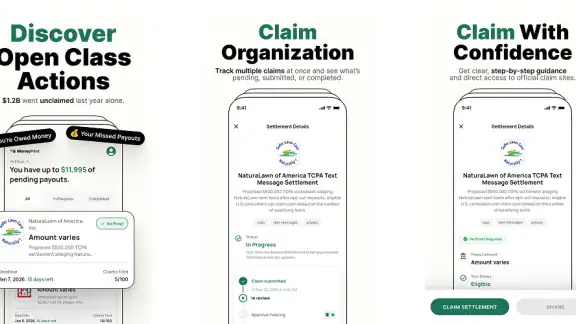
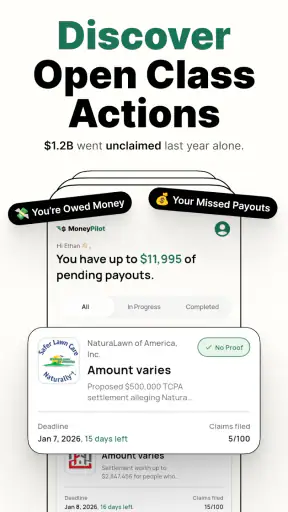
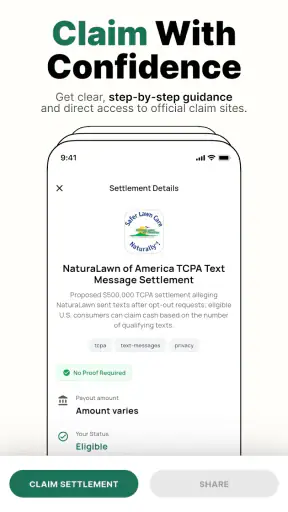
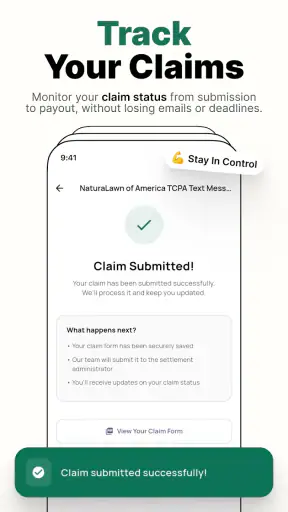
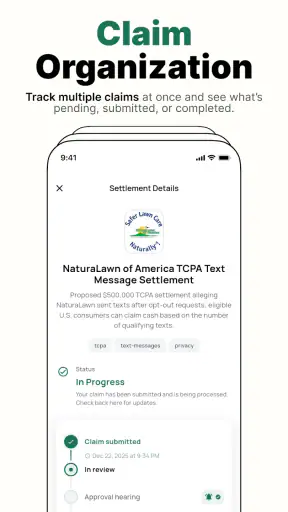
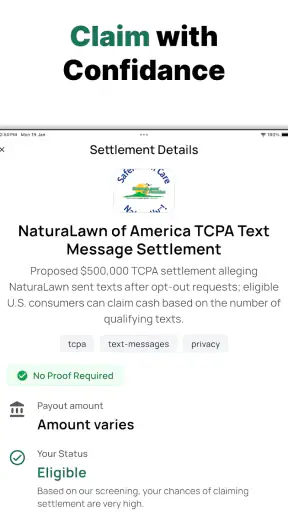
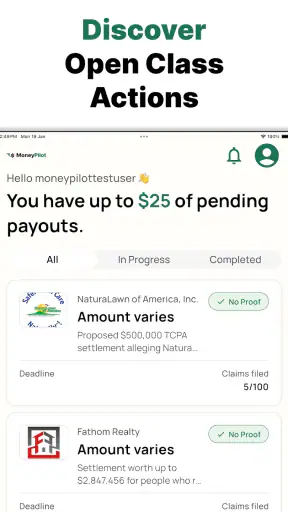
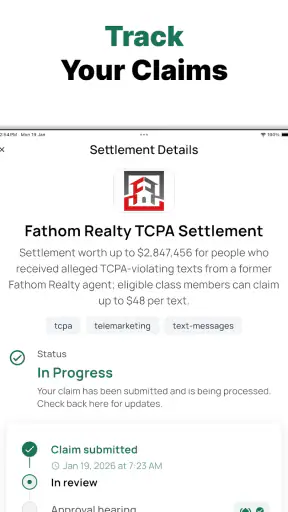
Details
- Rating
- 203.00 reviews
- Version
- 1.0.55
- Developer
- Bloom Processing
Analysis by Norviv
I approached MoneyPilot: Class Action as a practical finance app rather than a general budgeting tool. Its purpose is narrower and, for the right person, potentially more useful: helping you find and track claims, submit payout claims, and look for money connected with settlements. That focus immediately sets it apart from banking dashboards and expense trackers. I would not open it to monitor everyday spending; I would use it when I suspect I may qualify for a class-action payout and want a more organized way to follow the process.
The app is free to install, carries an Everyone content rating, and is developed by Bloom Processing. It has reached over 50 thousand installs and holds a 4.6 average from around 1.9 thousand ratings, which gives it a reassuring first impression without making it automatically right for every situation. My experience with this type of tool is that the real test is not the promise of finding money. It is whether the search, eligibility checks, claim submission, and follow-up remain clear when the user has incomplete information or runs into a stalled screen.
The most useful way to think about MoneyPilot is as a claim-organizing companion, not a guarantee of payment. A settlement may have strict eligibility rules, deadlines, documentation requirements, or a limited payout pool. The app can make the process easier to manage, but it cannot turn an ineligible purchase into a valid claim. That distinction matters, especially for anyone expecting an automatic refund simply because a case appears in the app.
Getting past the first points of friction
I’d use this section to focus on the small habits that make a claims workflow easier to manage: checking eligibility before entering details, keeping supporting records close at hand, and noting where a submission stands. Those steps help distinguish a genuine app snag from a question about the claim itself. From there, it makes sense to look at the setup checks that can prevent avoidable delays.
Where people are most likely to get stuck
The first obstacle is usually not technical. It is uncertainty about what information a claim requires. A user may remember buying a product or using a service but not remember the exact date, account, receipt, location, or payment method. In that situation, the temptation is to start entering guesses just to move forward. I would avoid that. A claim form is a poor place to improvise, and inaccurate details can create more trouble than an unfinished form.
I recommend gathering likely evidence before spending time on submission. Search old email receipts, order histories, bank or card statements, and loyalty-account records. If the claim concerns a subscription or online purchase, check the relevant account history rather than relying on memory. This is a small preparation step, but it makes the app feel much less frustrating because you are not constantly leaving the process to hunt for one missing detail.
Another common sticking point is confusing discovery with eligibility. Finding a settlement that sounds familiar does not mean the user qualifies. The wording of a case can refer to a particular product, time period, purchase method, location, or group of customers. I would read each requirement carefully and treat the app’s claim information as a starting point for verification, not as permission to submit automatically.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Users may also hesitate when a claim asks for information they did not expect. That does not necessarily mean the app is malfunctioning, but it is a moment to slow down. Check the field label, review the case instructions, and avoid entering sensitive information unless you understand why it is being requested and where it is being submitted. A finance-related app deserves the same caution as any service handling personal records.
Setup checks that save time later
Before using the app seriously, I would make sure the device is running Android 7.0 or newer, since that is the stated minimum operating-system requirement. If the app will not install or behaves strangely during launch, checking the operating-system version is more useful than repeatedly tapping the install button. It is also worth confirming that the device has a stable connection and enough free storage for normal app operation.
Keep the app updated to the current version, which is 1.0.55. An update is not a promise that every issue disappears, but it is a sensible first check when a page does not load, a form behaves inconsistently, or an older installation has been sitting untouched for a long time. I would also restart the app after updating instead of assuming the new version is active while an old session remains open.
For a smoother setup, I would use a reliable email address or contact method that I check regularly, if the app requests one for claim communication. The important point is consistency: use the same details you can access later, especially if a claim requires follow-up. A forgotten inbox or mistyped address can look like a missing payout when the real problem is that the user cannot see the relevant message.
One practical habit is to create a simple note outside the app containing the claim name, the date you started it, the information you used, and any confirmation reference shown after submission. Do not copy sensitive credentials into that note. The purpose is to create a lightweight record so you can distinguish a claim that was never submitted from one that is waiting for review or payment.
A better workflow for finding and submitting claims
I would begin with a focused search rather than browsing randomly. Think through products, services, subscriptions, or transactions that match the kinds of cases you may have seen recently. Then compare the app’s listing details with your own records. This approach reduces the risk of submitting claims based only on a familiar brand name while overlooking the dates or purchase conditions that actually determine eligibility.
When a possible match appears, read the requirements from beginning to end before entering information. Look for the qualifying period, the type of customer covered, the purchase or usage condition, and any evidence requested. If the app presents a submission path, treat it as a checklist. Complete one claim carefully rather than opening several and losing track of which details belong to which case.
A non-obvious advantage of this method is that it exposes weak matches early. If you cannot connect the case to a specific purchase, account, or period, that is a signal to pause. The time saved by abandoning an uncertain claim can be greater than the time spent forcing it through. MoneyPilot is more useful when it helps you make deliberate decisions than when it simply encourages more submissions.
For claims involving several purchases, keep your evidence organized by case instead of mixing everything into one folder. A separate note or folder for each claim can include receipts, statements, and the date of submission. I would avoid uploading duplicate or unrelated documents just because they are available. More paperwork is not automatically better; relevant paperwork is.
Recovering when a workflow breaks
If a claim page stops responding, I would first note the last completed step and avoid repeatedly submitting the same form. Close and reopen the app, check the connection, and return to the claim using the normal path. If the app shows a confirmation or reference, record it before trying anything else. Repeated taps can create uncertainty about whether a submission went through.
If the app appears to lose progress, reconstruct the workflow from your notes rather than starting blindly. Check whether the claim is already listed as active, submitted, or awaiting action. The exact wording may vary, but the principle is the same: confirm the current state before creating a second attempt. This is especially important when the claim involves a deadline or a limited submission window.
Users sometimes interpret a delayed result as a failed claim. Those are not always the same thing. A submission can be complete even when payment is not immediate, and an app screen may not be the only place where a claim’s status is communicated. I would keep the confirmation details and watch the contact method associated with the claim instead of assuming that a quiet period means rejection.
There is also a useful distinction between app recovery and claim recovery. Restarting the app can address a frozen interface, but it cannot correct an incorrect eligibility answer, missing document, or wrong payment detail. If the screen works but the claim is questioned, the next step is to review the case instructions and the information submitted, not to reinstall the application.
When the app is not the cause
Some problems sit outside MoneyPilot. A settlement administrator may take time to review submissions, a payment provider may delay delivery, or a case may have rules that prevent a payout even when the claim was submitted successfully. In those situations, reinstalling the app will not change the underlying process.
It is also possible for a user to search with an incomplete memory and conclude that the app missed a claim. Search results depend on the wording and details available. I would try alternate spellings, check the relevant dates, and search by the product or service rather than only by the company name. Still, I would not treat every similar-sounding result as a match.
Privacy and trust deserve a separate check. Before entering personal or financial information, read the on-screen explanation of why it is needed and confirm that you are using the intended claim process. Avoid sharing passwords, security codes, or unrelated account details. If a request seems disconnected from the claim itself, stop and investigate rather than assuming it is a normal step.
The app’s free price makes it easy to try, but users should still pay attention to any optional purchase screen. MoneyPilot includes in-app purchases ranging from $3.99 to $99.99 per item. I would not pay simply because a claim is visible or because a faster-looking path is offered. First decide whether the claim is relevant, whether the expected benefit justifies the charge, and whether the same submission can be completed through the ordinary process.
This is one of the clearest differences between a claim-finding app and a conventional personal-finance tool. A budgeting application measures spending patterns and helps plan future expenses. A bank app shows transactions and balances. MoneyPilot addresses a different problem: locating possible settlement opportunities and keeping track of the actions connected with them. If your goal is debt reduction, bill reminders, investment monitoring, or expense categorization, I would choose a dedicated tool instead.
Who will benefit most from it
I think the app is best suited to people who have several possible claims to investigate and want one place to organize the process. It can also help users who are willing to check eligibility carefully but do not want to search the wider internet repeatedly or maintain a scattered collection of bookmarks and notes.
It is particularly practical after a major change in your digital or shopping history, such as closing an old account or changing payment methods. Those transitions can make records harder to find later, so reviewing available claims while receipts and account information are still accessible is a sensible habit. The app does not replace those records, but it gives the search a more defined workflow.
A realistic example would be someone who notices several settlement notices over the course of a year. Instead of submitting each one immediately, they open MoneyPilot, compare the eligibility language with old order emails, and record which cases require proof. They submit only the claims they can support, save each confirmation, and check the relevant contact channel later. That process is slower than tapping through every result, but it is far more reliable.
Who should choose another option
I would skip this app if you expect guaranteed money, instant payments, or automatic eligibility. Settlement claims are conditional by nature, and no organizer can remove those conditions. I would also avoid relying on it as your only recordkeeping system if you handle many claims, because a separate, clearly labeled archive of receipts and confirmations remains valuable.
People who are uncomfortable reviewing legal or eligibility wording may prefer to handle claims directly through the official case process or ask a trusted professional for help. The app may make discovery more convenient, but convenience is not a substitute for understanding what you are agreeing to submit.
Finally, if you only want a standard finance dashboard, MoneyPilot will feel specialized rather than comprehensive. Its value comes from the claim workflow. For everyday money management, a banking app, spreadsheet, or budgeting service will usually be a better fit.
My practical verdict
After looking at the complete experience, I see MoneyPilot as a focused tool with a clear use case and a few predictable points where users need patience. The strongest benefit is organization: it can help turn an easily forgotten settlement search into a sequence of checks, submissions, and follow-ups. The weakest point is the expectation gap. Anyone treating a listed case as guaranteed income will probably be disappointed.
The free entry point and Everyone rating make it approachable, while the current release gives Android users a straightforward way to try the workflow on supported devices. Its 4.6 average is encouraging, but I would judge it by your own situation: do you have possible claims to investigate, records to support them, and the patience to read the requirements?
My recommendation is to try it with one well-documented claim first. Prepare your records, verify the qualifying details, note the submission status, and avoid optional spending until you understand what the app is doing for you. If that first experience helps you stay organized, it may earn a regular place in your finance toolkit. If you are looking for budgeting, account management, or guaranteed payouts, I would choose a different kind of app instead.
In short, MoneyPilot: Class Action is most valuable when used as a careful claims tracker rather than a promise of found money. I would recommend it to an organized user who wants help discovering and following settlement opportunities, provided they remain responsible for checking eligibility, protecting personal information, and keeping their own records.
Frequently Asked Questions
01What is MoneyPilot: Class Action, and what does it do?
MoneyPilot: Class Action is designed to help users discover and track potential class-action settlements and other consumer compensation opportunities. The app may present information about eligibility, claim deadlines, settlement amounts, and required documentation. Before relying on any listing, users should read the official settlement notice carefully, because the app is an information and organization tool rather than a guarantee that a claim will be approved or paid.
02Is MoneyPilot: Class Action free to download and use?
The app may be available to download without an upfront charge, but users should review its current store listing and in-app terms for any premium features, subscriptions, advertising, or optional purchases. Availability and pricing can change by country or platform. It is also important to check whether any service fee applies to a claim-related feature and to understand cancellation terms before entering payment details.
03Can MoneyPilot: Class Action guarantee that I will receive settlement money?
No application can guarantee that a user will receive compensation from a class-action settlement. Eligibility is determined by the official settlement administrator, court-approved rules, and the information submitted in the claim. MoneyPilot may help users find opportunities, organize deadlines, or understand basic requirements, but approval, payment timing, and the final amount depend on the specific case and the accuracy of the submitted documentation.
04Is it safe to provide personal information in MoneyPilot: Class Action?
Users should treat requests for personal, financial, or legal information carefully. Before submitting anything, review the app’s privacy policy, developer details, permissions, and the identity of the official settlement administrator. Avoid sharing passwords, banking login credentials, or unnecessary sensitive data. When a claim requires information, confirm that the request appears on the official settlement website and that the connection and contact details are legitimate.
05How do I know whether a class-action opportunity shown in the app is legitimate?
Use MoneyPilot as a starting point, but verify every opportunity independently before submitting a claim. Check the case name, court information, official settlement website, administrator, eligibility dates, deadline, and contact details. Be cautious of requests for upfront payment, pressure to act immediately, guaranteed payouts, or links that look suspicious. If the information conflicts with the official court-approved notice, rely on the official source.


